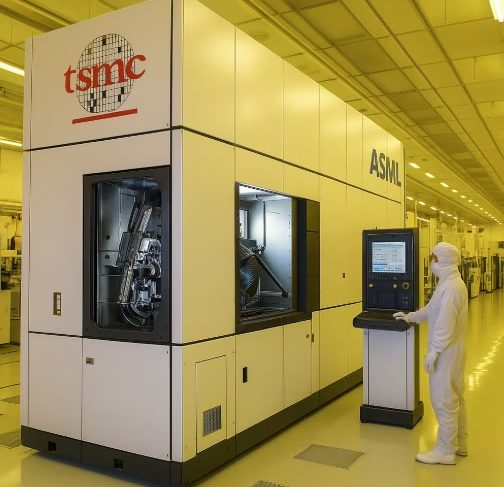
Let me tell you the tale of the little island that could — Taiwan — home to a company that doesn’t sell shoes, ships, or social media, but sells the future one microscopic chip at a time. TSMC is its name, and it’s become the beating silicon heart of the modern world. Every smartphone in your hand, every data center dreaming AI dreams, even your car that thinks it’s smarter than you — all powered by TSMC’s handiwork.
Donald Trump — love him or loathe him — calls it the most important company on Earth. And for once, the man might not be exaggerating. Because if you unplug TSMC, you don’t just switch off Taiwan; you dim the lights on global progress. But here’s the kicker: the world’s most vital company also sits on the world’s most dangerous fault line, both figuratively and geopolitically. That makes investing in it feel like buying a front-row seat to a symphony — with a slight chance of missile fire.
So yes, I’m planning to buy some more. Not because it’s safe, but because it’s essential. The only real question is when. Before the tariffs? After the tanks? Or when sanity and silicon finally learn to share a border?
Now, I’m no soothsayer, and I’ve long since retired my crystal ball — mostly because it was made in China and cracked. But I know this: there are two kinds of companies in this world — those that follow trends, and those that build the roads the trends drive on. TSMC doesn’t just build the road; it pours the concrete, lays the fiber, and charges tolls to Apple, NVIDIA, and Amazon for the privilege of driving.
Sure, it’s in a risky neighborhood. Sure, it’s first on the chopping block in any trade war or cross-strait crisis. But when the world runs on chips and one company makes the smartest ones, you don’t ignore it — you watch it closely and keep your powder dry. I’ll buy more when the price dips, when the winds settle, or when the storm is priced in.
Some companies are too big to fail. TSMC? It’s too important to ignore.
The Geopolitical Shadow
TSMC’s headquarters in Taiwan is both its identity and its greatest risk. Any conflict or blockade across the strait would shatter the global chip supply chain overnight. Washington and its allies are pouring money into domestic chipmaking, but replicating TSMC’s capabilities is brutally difficult — the know-how took decades to accumulate. TSMC is hedging by building fabs in Arizona, Japan, and Germany, spreading some capacity beyond the island. Smart move, but let’s be honest: the crown jewels stay in Taiwan.
The Competition Isn’t Close
TSMC controls roughly 60% of the global foundry market, and at the leading edge it’s barely a contest. Samsung Foundry chases TSMC at 3nm and 2nm but keeps stumbling on yields. Intel is barging back into contract manufacturing with government money behind it, yet execution remains the question mark. GlobalFoundries, UMC, and China’s SMIC compete at mature nodes — irrelevant at the frontier. Even giants like Apple and Amazon design their own silicon but still queue up at TSMC’s door to have it built. Nobody else can do what TSMC does at the scale TSMC does it.
The Roadmap: 3nm Today, 2nm Tomorrow
TSMC is shipping 3nm chips now and moving toward 2nm production, leading the industry in yields and reliability — the unglamorous metrics that actually decide who wins. Its advanced packaging technology, like CoWoS, has become essential for AI accelerators; NVIDIA’s AI boom runs on TSMC’s packaging as much as its transistors. The roadmap stretches to 2nm and beyond, and every step keeps TSMC one generation ahead of everyone else.
The Client List Reads Like a Who’s Who
Apple accounts for roughly a quarter of TSMC’s revenue — the exclusive manufacturer of Apple’s A-series and M-series chips. NVIDIA is the fastest-growing customer, riding the AI wave. AMD, Qualcomm, and MediaTek fill out the roster with steady volume. High-performance computing now makes up over half of TSMC’s revenue, driven by AI and data-center demand — a healthy shift away from maturing smartphone volumes.
The flip side is concentration risk. Apple and NVIDIA together could approach half of revenue within a couple of years. That’s a wonderful problem to have until it isn’t — if either giant stumbles or shifts sourcing, TSMC feels it. So far the symbiosis has been golden: record 2024 earnings were powered by Apple’s iPhone launch and NVIDIA’s AI explosion. But investors should keep one eye on Cupertino’s silicon roadmap and the other’s on AI demand curves.
What About the Price?
TSMC trades at around 22 times trailing earnings, with forward multiples in the high teens — reasonable next to NVIDIA’s mid-20s forward multiple, and far saner than Intel’s. Expected revenue growth runs in the high teens annually, driven by AI demand and the 2nm ramp. The financials are best-in-class: 40%-plus margins, return on equity above 30%. You’re paying a fair price for the best business in semiconductors, with a geopolitical discount baked in.
Tariffs, Export Controls, and the Tech War
TSMC sits dead center in the U.S.–China tech brawl, and the crossfire is real. American export controls have already cost TSMC its Huawei business — once 14% of revenue — and now bar leading-edge chips from Chinese customers without licenses. China-based clients have shrunk to roughly 10–15% of sales, mostly mature-node work. The controls also kneecap China’s domestic champions: SMIC can’t buy EUV lithography machines, which locks in TSMC’s lead. Painful in the short term, protective in the long term.
Then there’s tariff talk. Proposals for steep duties on Taiwanese chips would function as a massive tax on iPhones, PCs, cars, and data centers — raising U.S. chip prices by half or more, according to industry studies. It would punish American consumers and tech companies far more than TSMC, which could accelerate its Arizona output (exempt as Made-in-USA) and serve other markets from Taiwan. The consensus: extreme tariffs would backfire, so they’re unlikely — but moderate measures and endless political noise are guaranteed.
Beijing has its own retaliation toolkit: export curbs on gallium and germanium, potential squeezes on chip chemicals, selective boycotts. Mostly symbolic so far — TSMC has stockpiles and alternative sources — but it adds friction and reminds everyone the supply chain is a weapon now.
The Bottom Line
TSMC stands alone at the pinnacle of semiconductors, with a technological and market position no rival can match. Its dominance — 3nm today, 2nm coming — puts it at the heart of every major tech trend: AI, 5G, autonomous vehicles, high-performance computing. The growth story is intact, the financials are superb, and governments and customers alike have every incentive to keep TSMC thriving.
But go in with eyes open. The China–Taiwan risk is low-probability, catastrophic-impact — the kind you can’t diversify away. Trade frictions will keep generating volatility. Samsung and Intel aren’t standing still, and even Apple flirts with second sources. TSMC has to execute its node transitions flawlessly, every time.
For a risk-tolerant investor, TSMC is a chance to own a cornerstone of the digital economy’s future at a reasonable price. Just don’t kid yourself about the neighborhood. Watch the politics, watch the customers, watch the technology — and when the storm gets priced in, that’s when you buy.